Ashok Leyland Faces Production Slowdown Ahead as Cyclical Downturn Threatens Indian Commercial Vehicle Sector

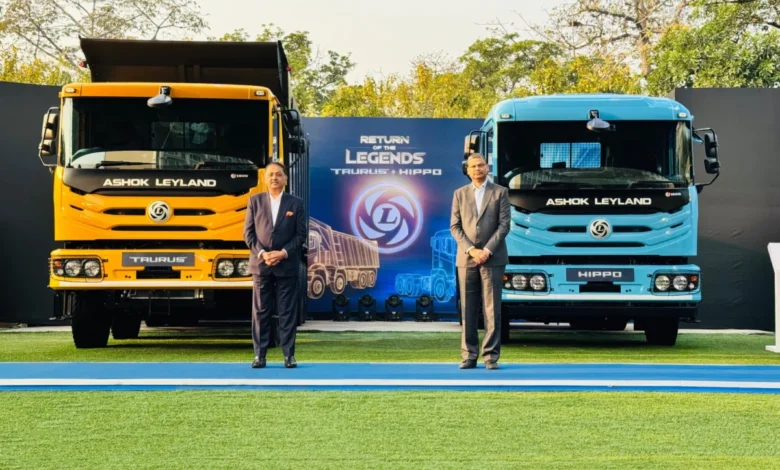
Commercial vehicle manufacturing in India is bracing for a period of adjustment following a period of unprecedented growth, with industry projections indicating that major original equipment manufacturer Ashok Leyland is set to encounter a significant, multi-year production contraction. According to recent market intelligence reports from Automotive World detailing the trajectory up to 2031, the company is poised to navigate a cyclical downturn primarily driven by softening demand in the domestic medium-haul segment. While the automaker recently celebrated a historic milestone by scaling its production to a record 220,600 units in the 2025/26 financial year—marking a robust 12.6 percent year-on-year increase—the immediate outlook suggests a starkly different economic reality for the upcoming fiscal cycles.
The anticipated cooling off of production lines follows a turbulent yet lucrative era for the Indian automotive industry, characterized by regulatory shifts, fiscal interventions, and evolving macroeconomic indicators. Analysts monitoring the sector emphasize that manufacturing highs are frequently followed by cyclical corrections, particularly within the heavy and medium commercial vehicle categories that serve as the economic lifeblood of the nation’s logistics and supply chain networks. As Ashok Leyland prepares to steer through these headwinds, industry stakeholders are closely examining the multifaceted catalysts behind the forecasted stagnation and subsequent decline, weighing the resilience of alternative segments such as light commercial vehicles and electric buses against broader macroeconomic pressures.
Chronology of Growth and the Fading Fiscal Catalyst
The trajectory of Ashok Leyland over the mid-2020s serves as a textbook illustration of how fiscal policy and industrial demand intersect in emerging markets. Throughout the 2024/25 and early 2025/26 periods, the company experienced a sharp surge in factory output, fueled largely by a combination of fleet modernization initiatives, post-pandemic economic recovery, and critical government interventions. A pivotal moment in this expansion occurred in October 2025, when sweeping Goods and Services Tax (GST) reforms implemented by the Indian government significantly lowered the acquisition costs of commercial vehicles. This reduction acted as an immediate stimulus, encouraging fleet operators to fast-track long-delayed replacement cycles and expand their operating capacities.
However, the expansive momentum generated by the October 2025 tax cuts is now displaying clear signs of exhaustion. Automotive World’s long-range forecasting models indicate that the initial wave of pent-up demand has been largely absorbed by the market. Consequently, the production growth rate for Ashok Leyland is projected to decelerate dramatically to a meager 0.8 percent in the 2026/27 financial year, capping total output at approximately 222,300 units. This near-stagnation is expected to be the prelude to a more pronounced contraction, with production volumes slated to follow a downward trajectory for two consecutive fiscal years as fundamental market indicators cool.
Sector-Specific Pressures: The Medium-Haul Dilemma
At the heart of the forecasted downturn is the medium-haul commercial vehicle segment, traditionally a core pillar of Ashok Leyland’s commercial strength. Freight demand indicators across major Indian industrial corridors have begun to soften, reflecting broader moderation in manufacturing output and consumption spending. As fleet operators witness stabilizing freight rates coupled with escalating operational expenses, willingness to invest in new medium-haul tonnage is diminishing rapidly.
Projections indicate that the medium-haul commercial vehicle category will bear the brunt of the impending contraction. Output within this specific division is anticipated to plummet by 11 to 12 percent during the 2027/28 financial year. The downward slide is projected to reach its trough in the subsequent fiscal year, with production bottoming out at approximately 91,200 units. This sharp contraction will test the financial agility and operational flexibility of the manufacturer, compelling management to reallocate resources and adjust assembly line efficiencies to mitigate margin erosion.
Divergent Fortunes: Buses and Light Commercial Vehicles as Buffers
While the medium-haul and heavy truck segments face formidable macroeconomic headwinds, other divisions within Ashok Leyland’s comprehensive portfolio are expected to display greater resilience, acting as vital buffers against a steeper corporate-wide decline.
The bus segment, for instance, presents a contrasting narrative. Industry analysts suggest that bus production may register modest growth during the 2027/28 financial year before experiencing a relatively mild downturn. This relative stability is underpinned by several structural drivers, most notably aggressive state-level electrification tenders aimed at modernizing public transit fleets across urban centers. Furthermore, stringent regulatory mandates—such as the enforcement of a strict 15-year age limit for government-operated buses—have created an artificial and necessary replacement cycle that municipal transport undertakings must fulfill, thereby insulating bus manufacturers from purely cyclical market swings.
Concurrently, the light commercial vehicle (LCV) division is projected to maintain a broadly stable output profile throughout the broader market dip. This resilience is heavily supported by strategic product portfolio enhancements, including the market integration of the popular Saathi model and a planned strategic entry into the lucrative 4-to-6-tonne weight category. By diversifying deeper into the sub-one-tonne and intermediate LCV spaces, Ashok Leyland has successfully captured the surging demand for hub-and-spoke distribution models, driven largely by the explosive growth of e-commerce and last-mile delivery networks in tier-2 and tier-3 Indian cities.
Strategic Implications and Broader Industry Analysis
The impending cyclical contraction at Ashok Leyland carries broader implications for the Indian automotive manufacturing ecosystem and the nation’s wider economic indicators. Commercial vehicle sales and production volumes are historically recognized as reliable leading indicators of economic health, reflecting corporate confidence, infrastructure development spending, and industrial freight velocity. A two-year production decline for a major market participant suggests a period of consolidation across the broader logistics and transportation sectors.
From an operational standpoint, automotive industry observers note that manufacturers today are better equipped to handle cyclical downturns compared to previous decades. Companies have increasingly focused on lean manufacturing principles, digital supply chain integration, and non-cyclical revenue streams such as aftermarket parts, digital fleet management services, and international exports. By expanding its global footprint into select markets across Africa, the Middle East, and Southeast Asia, Ashok Leyland has sought to de-risk its revenue profile from localized domestic market fluctuations.
Furthermore, capital expenditure plans may undergo strategic recalibration. While short-term volume growth is projected to stall, long-term technological transitions—particularly research and development investments in battery-electric vehicles (BEVs), hydrogen fuel cells, and advanced driver assistance systems (ADAS)—remain non-negotiable priorities. Industry leaders must balance the immediate need for cost containment with the imperative to stay ahead of tightening emissions standards and evolving regulatory frameworks.
Path to Recovery: Looking Toward 2031
Despite the looming shadows of a two-year production contraction, long-term market fundamentals for the Indian commercial vehicle sector remain fundamentally sound. The underlying growth drivers of the Indian economy—including sustained investments in national infrastructure, highway expansion, mining activities, and urbanization—ensure that commercial mobility will experience structural demand over the next decade.
According to Automotive World’s comprehensive OEM outlook, the cyclical correction is expected to run its course by the end of the decade. A robust market recovery is anticipated to commence from the 2029/30 financial year, propelled by pent-up replacement demand, macroeconomic stabilization, and the mainstream adoption of next-generation commercial platforms. As the logistics sector modernizes and fleet operators upgrade to cleaner, more efficient technologies, Ashok Leyland’s production capabilities are projected to rebound strongly. Current forecasts indicate that total vehicle output could surpass previous records, potentially climbing to a new historical high of 242,400 units by the 2030/31 financial year. Until then, the manufacturer must navigate the intervening valley with disciplined cost management and strategic market diversification.
Related posts: