Stocks are in a late-stage bubble and poised to crash 21% next year, while Treasury yields above 5% will signal a new era of tight money, analysts say | Fortune

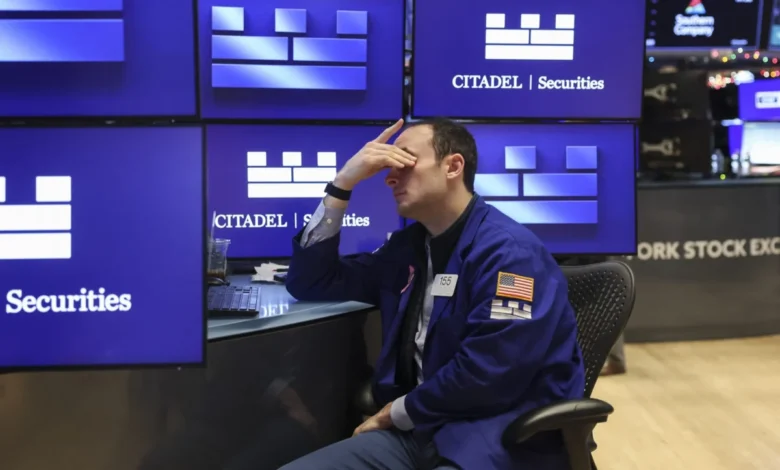
A Forecast for Volatility
James Reilly, a senior markets economist at Capital Economics, has maintained a sobering outlook regarding the immediate future of equity markets. While Reilly concedes that the S&P 500 may reach a target of 8,250 by the end of 2026—representing a 7.7% increase from current levels—he warns that this growth is largely a manifestation of a "blow-off rally." His analysis points to a subsequent contraction of 21%, projecting the index to plummet to 6,500 by the conclusion of 2027.
Reilly’s diagnosis is rooted in technical indicators that bear a striking resemblance to previous historic market peaks. "On balance, we think the data look consistent with a late-stage bubble," Reilly noted in a recent briefing. "Most of the factors we consider are at, or close to, levels that have preceded past stock market peaks."
The Anatomy of an AI Bubble
The concerns voiced by analysts are not merely speculative; they are predicated on a confluence of fundamental metrics that have historically signaled market fragility. Among the most cited concerns are:
- Valuation Extremes: The cyclically adjusted price-to-earnings (CAPE) ratio, a key metric for determining long-term valuation, is currently hovering near levels last seen during the dotcom bubble of the late 1990s. Furthermore, the valuation of the S&P 500 relative to Treasury bonds has reached similar extremes, suggesting that stocks are increasingly expensive even when risk-free rates are taken into account.
- Earnings Sustainability: Forward 12-month earnings-per-share (EPS) projections for the S&P 500 are currently aligned with the peak of the dotcom era. Critics argue that these forecasts rely on aggressive AI-driven revenue growth that may not materialize as quickly as corporate guidance suggests.
- Cash Flow Constraints: A critical point of contention is the massive capital expenditure required to maintain AI infrastructure. Hyperscalers—the massive cloud computing providers driving the current boom—are seeing their free cash flow margins compress. Estimates suggest that the combined free cash flow for these industry giants could turn negative in 2027, raising questions about the long-term viability of their current spending trajectories.
- Market Concentration: The reliance of the broader market on a handful of mega-cap technology stocks has reached record levels. Historically, such narrow market participation is indicative of a rally that lacks structural support and is prone to sudden, sharp reversals.
- Equity Issuance: A surge in IPOs and follow-on equity offerings has historically served as a harbinger for the end of a bull market. The current pipeline of new listings suggests that market participants are rushing to capitalize on high valuations, a phenomenon that has historically preceded market corrections by only a matter of months.
The Macroeconomic Pressure Point
While the internal mechanics of the stock market are flashing warning signs, external macroeconomic factors are compounding the risk. The yield on the 10-year U.S. Treasury note has climbed to 4.97%, placing it on the threshold of a critical psychological and economic barrier: the 5% mark.
Ruchir Sharma, Chairman of Rockefeller International, has been vocal about the implications of this development. In a recent analysis, Sharma suggested that a "decisive breach" of the 5% yield level would represent the end of the era of cheap capital that has enabled the AI gold rush. "This breach would signal the start of a new era of tighter money, in which AI mega projects will be harder to fund," Sharma wrote.
The implications of 5% yields are multi-faceted. First, high borrowing costs increase the hurdle rate for new projects, making it more difficult for tech firms to justify the massive debt loads they have incurred. Second, high yields make bonds a more attractive alternative to equities, potentially triggering a rotation out of the stock market. Finally, as the U.S. national debt exceeds 100% of GDP, the government’s own interest expense becomes a significant fiscal burden, further constraining liquidity in the broader economy.
Sentiment Shift Among Market Bulls
Even veteran observers of the market who have historically maintained a bullish stance are beginning to temper their enthusiasm. Ed Yardeni, a widely respected Wall Street strategist, recently adjusted his probability assessments for the "Roaring 2020s" market scenario. Yardeni lowered his confidence in a continued bull market from 80% to 70%, while simultaneously raising the probability of a bearish outcome from 20% to 30%.
In his commentary, Yardeni acknowledged that the recent volatility in oil prices and the upward pressure on bond yields have created an environment that is increasingly difficult to navigate. "Admittedly, recent developments in the oil and bond markets are unnerving," he noted, signaling a broader shift in institutional sentiment.
Chronology of the AI Rally
The trajectory of the current AI boom can be categorized into three distinct phases:
- The Inception (2023): Initial excitement surrounding generative AI sparked a surge in semiconductor and software stocks, as companies scrambled to integrate new technologies into their operations.
- The Expansion (2024–2025): Capital expenditure ballooned as hyperscalers invested billions into data centers and hardware, leading to a broadening of the rally to include infrastructure and energy sectors.
- The Late-Stage (2026): Market participants shifted focus toward monetization. As expectations for near-term revenue growth hit a ceiling, the market became increasingly sensitive to interest rate fluctuations and macroeconomic data.
Broader Economic Implications
The transition from a growth-at-all-costs environment to one dictated by capital discipline has profound implications for the global economy. Should the AI bubble begin to deflate, the impact would likely be felt across several sectors beyond technology.
Institutional investors, including pension funds and insurance companies that have increased their exposure to private equity and venture capital to capture AI-related gains, may face liquidity constraints. Furthermore, the reliance of the U.S. economy on robust equity markets to maintain consumer confidence and business investment could lead to a broader economic slowdown if the current rally terminates abruptly.
While proponents of the AI revolution argue that the productivity gains from the technology will eventually justify the current valuations, the timing of such benefits remains uncertain. Economists note that historically, major technological shifts—such as the introduction of electricity or the internet—often take decades to translate into meaningful, broad-based productivity growth. The current market, however, is pricing in these gains on a much more compressed timeline.
Conclusion: A Period of Strategic Recalibration
As 2026 draws to a close, the consensus among cautious market observers is not necessarily that the AI revolution is a failure, but rather that it has been priced to perfection. The disconnect between current valuations and the reality of rising borrowing costs, combined with the extreme concentration of market leaders, creates a precarious environment.
Investors are now tasked with navigating a period that is likely to be characterized by heightened volatility. As the 5% Treasury yield barrier looms, the financial markets are preparing for a potential "re-rating" of assets. Whether this leads to a soft landing or a more pronounced correction remains the central question for the coming year. For now, the prevailing advice from those tracking the bubble indicators is clear: monitor debt-servicing costs, watch for a broadening of market participation, and remain prepared for a shift in the macroeconomic landscape that has defined the last decade.