Insight Partners Co-Head Devin Parekh Discusses AI Realities, Portfolio Strategy, and Venture Liquidity at StrictlyVC New York

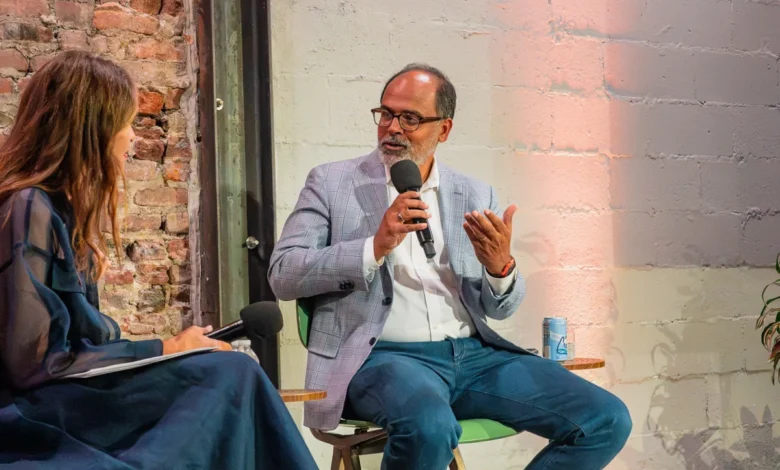
Insight Partners has long maintained a reputation for quiet execution in an industry often dominated by loud self-promotion and social media grandstanding. Over a span of 26 years, Devin Parekh has co-run the heavyweight investment firm through numerous market cycles, steering clear of the viral podcast circuit while managing a staggering $90 billion in assets under management (AUM). During a candid sit-down interview with TechCrunch at the StrictlyVC event in New York City, Parekh broke from the firm’s traditionally low-profile stance to address the state of the venture capital landscape, artificial intelligence valuations, market concentration risks, and the critical importance of returning liquidity to limited partners (LPs).
The StrictlyVC gathering, hosted in Manhattan, brought together top-tier venture capitalists, founders, and industry analysts to evaluate the shifting dynamics of tech investing in an era defined by generative AI hyper-growth, shifting interest rates, and regulatory scrutiny. Against this backdrop, Parekh offered a pragmatic look inside Insight Partners’ multifaceted operational playbook.
Navigating AI Risks, Healthcare Transformation, and Societal Evolution
The discourse surrounding artificial intelligence has increasingly been dominated by existential warnings from researchers and ethicists. Most recently, a high-profile departure by an Anthropic researcher who publicly warned against the dangers of self-improving AI sparked widespread debate across the technology sector.
When pressed on whether these concerns amount to hysteria or warrant genuine alarm, Parekh adopted a measured, risk-balanced perspective. He acknowledged that theoretical dangers exist—such as a non-state actor leveraging open-source models to synthesize biological threats. However, he argued that these risks must be weighed against the transformative, life-saving potential of the technology.
Parekh pointed to the pharmaceutical and medical sectors as primary beneficiaries of accelerated computational capacity. Drawing on his experience as a board member at NYU Langone Health, he highlighted how machine learning algorithms can analyze vast repositories of patient data to identify latent medical vulnerabilities long before symptoms manifest. For instance, screening millions of patient records can allow clinicians to alert an asymptomatic individual to a high probability of a cardiac event years in advance.
Furthermore, Parekh emphasized that demographic realities necessitate the adoption of AI-driven tools. With aging populations across developed nations and a persistent shortage of medical professionals, scaling healthcare infrastructure is impossible without technological leverage. He likened current technological anxieties to historical debates surrounding next-generation drone warfare or previous industrial transitions, noting that human society has consistently adapted to new risk thresholds while progressively raising global living standards.
The Case for Quiet Performance and Flexible Fund Allocation
With $90 billion in AUM, Insight Partners ranks among the elite class of global software investors. Yet, the firm consciously avoids the public posturing common among peer funds. Parekh criticized the tendency of contemporary venture capitalists to posture as universal experts on complex global events, ranging from macroeconomic geopolitics to epidemiological crisis management.
Instead of chasing algorithmic engagement on social media platforms, Insight relies on the verifiable performance of its portfolio companies. The firm’s investment strategy rejects rigid geographic or directional quotas, favoring a fluid allocation model that adapts dynamically to macroeconomic headwinds.
This temporal approach means that the distribution of early-stage venture capital, growth equity, and buyout financing shifts across successive fund vintages. According to Parekh, the buyout market has faced significant compression due to elevated interest rates, restrictive debt financing conditions for software enterprises, and declining exit multiples. Consequently, Insight has refrained from executing a major buyout transaction since 2024.
Shifting Downstream: The Pivot to Early-Stage Investing Amid Inflated Valuations
Venture valuations, particularly within the artificial intelligence ecosystem, have accelerated at a pace reminiscent of the frothy market conditions of 2021—a historical parallel that ultimately preceded a severe market correction. In traditional venture investing, participating in follow-on funding rounds typically entails paying a higher price in exchange for reduced risk, backed by newly generated operational data. However, the current velocity of venture financing often leaves little time for incremental data accumulation, forcing investors to pay premium valuations without a corresponding decrease in execution risk.
To mitigate this exposure, Insight Partners has increasingly leaned into early-stage investments. By deploying scale funds into smaller, initial checks—ranging from $20 million to $25 million rather than committing hundreds of millions upfront—the firm maintains the flexibility to concentrate capital on proven winners. Parekh cited the cybersecurity firm Wiz as a prime example of this strategy, where an initial Series A commitment was successfully scaled through subsequent follow-on checks. This asymmetric risk profile ensures that even if an early-stage bet fails, the downside is heavily cushioned relative to the fund’s overall scale.
Global Talent Dispersion and Regional Specialization
Geographic concentration remains a central theme in modern technology investing, particularly within frontier infrastructure. While Parekh noted that foundational AI infrastructure talent remains heavily anchored in the San Francisco Bay Area—prompting even young investors to relocate to the region—vertical-specific applications exhibit far greater geographic diversity.
For instance, financial technology talent clusters heavily in New York, as seen with companies like Ramp. This specialization allows investors to source high-growth opportunities globally rather than remaining tethered exclusively to Silicon Valley. As an illustration of international dealmaking, Parekh discussed Insight’s pursuit of Legora, a buzzy European legal-tech startup based in Stockholm. Despite dispatching partner Jeff Horing to Sweden to pitch the founder, Insight ultimately lost the deal to General Catalyst. Parekh displayed a pragmatic attitude toward the loss, noting that global markets are vast and competitive defeats are an inevitable component of institutional investing.
Competing Interests and the Evolution of Multi-Model Portfolios
Historically, venture capital taboos strictly prohibited investing in direct competitors. However, the maturation of the generative intelligence market forced a structural reassessment of this norm. Insight Partners holds stakes in both OpenAI and Anthropic, two of the primary heavyweights in the foundational model landscape.
Parekh explained that internal deliberations primarily centered on investment timing rather than philosophical conflicts. Early-stage investors—such as Khosla Ventures, which backed OpenAI’s Series A—face natural structural barriers that preclude them from funding direct rivals. However, at later stages, institutional investors function less like active governance participants and more like conventional equity holders.
Insight’s thesis identified OpenAI as the dominant consumer-facing player, while Anthropic carved out a distinct enterprise strategy. As foundational model developers required monumental capital infusions ranging from $30 billion to $100 billion, traditional demands for exclusivity became untenable. Nevertheless, at earlier funding tiers (Series A and B), strict information-sharing barriers and non-compete parameters remain firmly in place to protect sensitive intellectual property.
The Concentration Risk Dilemma and LP Liquidity Pressures
The broader venture capital landscape has become heavily lopsided. During the first half of the year, foundational model giants OpenAI and Anthropic commanded roughly half of all venture capital deployment globally. This extraordinary concentration of capital has intensified discussions surrounding portfolio risk among institutional limited partners (LPs).
While diversified portfolios buffer firms like Insight against acute concentration risk, some newer venture funds have structured their entire fundraising pitch around allocating up to 40% of their total capital into a single foundational model developer. Parekh cautioned that while such concentrated bets can yield extraordinary short-term returns if the underlying companies succeed, long-term venture performance has historically favored disciplined diversification. Running fund vintages successfully requires a multi-generational horizon rather than reliance on a single binary outcome.
Beyond deployment, the imperative of liquidity has re-emerged as a dominant industry concern. Many funds raised during the 2021–2023 capital boom have struggled to distribute cash back to their LPs. First- and second-time fund managers face severe headwinds in raising subsequent vintages due to an inability to demonstrate realized returns (DPI, or distributed to-paid-in capital).
Parekh emphasized that returning capital is a core fiduciary duty. Over the preceding two years, Insight Partners successfully returned over $20 billion to its LPs via strategic secondary sales and public listings, with billions more in distributions pending. He advised founders and portfolio managers to proactively de-risk positions and realize gains, noting that public markets and secondary transactions provide essential liquidity mechanisms for long-term sustainability.
Valuation Realities and the Approaching Public Market Wave
As discussions turn toward potential initial public offerings (IPOs) for market leaders like Anthropic and OpenAI—both of which have scaled to historic valuations within a few short years—industry observers are evaluating the broader implications for public-market investors. Parekh observed that while a handful of trillion-dollar tech titans can absorb public market liquidity seamlessly, the true test will be how public exchanges digest the secondary tier of high-growth technology companies.
The extraordinary growth trajectories of modern tech enterprises—scaling from inception to tens of billions in revenue within years—will inevitably normalize. As these organizations transition into traditional, mature growth companies, public markets will remain essential for providing structural liquidity and price discovery.
Ultimately, Parekh’s insights at StrictlyVC underscore a return to traditional venture fundamentals: balancing technological optimism with rigorous risk management, prioritizing long-term portfolio diversification over transient hype cycles, and maintaining an unwavering commitment to returning capital to investors in an ever-shifting macroeconomic environment.