New York appeals court dismisses lawsuit challenging Mayor Zohran Mamdani’s pied-a-terre tax rollout

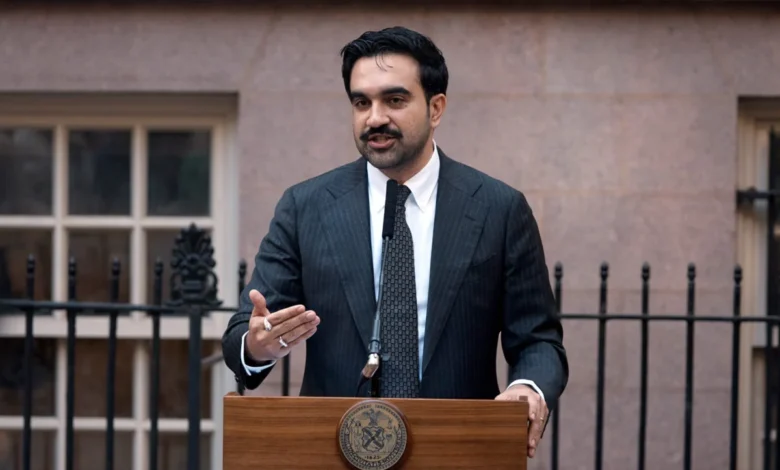
A unanimous decision from the Appellate Division, Second Department, has delivered a significant victory to the administration of Mayor Zohran Mamdani, effectively neutralizing a high-profile legal challenge against the city’s controversial pied-a-terre tax. The ruling, handed down this past Wednesday, reverses a previous decision by Staten Island Supreme Court Justice Wayne Ozzi that had placed a temporary injunction on the tax’s implementation. By finding that the plaintiffs lacked the legal standing to sue, the four-judge panel has cleared a major hurdle for the city as it moves to collect revenue from owners of luxury second homes.
The litigation, which originated in August, centered on the Department of Finance’s (DOF) methodology for identifying properties subject to the new surcharge. Seven homeowners, represented by prominent attorney and former First Deputy Mayor Randy Mastro, argued that the city’s administrative process was flawed and burdensome. Specifically, the plaintiffs contended that the DOF acted improperly by mailing out notices to approximately 17,000 property owners—many of whom were primary residents—and placing them on a supplemental roll of 900,000 potential targets without first verifying their residency status through existing income-tax records.
However, the appellate court declined to reach the merits of whether the city’s administrative procedures were technically deficient. Instead, the court focused on the threshold issue of standing, concluding that the plaintiffs had failed to demonstrate a "concrete injury" sufficient to warrant judicial intervention. The judges characterized the notices as purely informational, akin to a standard debt collection communication, and emphasized that the legislative framework for the tax explicitly anticipated the possibility of administrative inaccuracies by including an exemption process.
A Chronology of the Pied-a-Terre Tax Rollout
The legal skirmish is the latest development in a protracted debate over tax policy in New York City. The pied-a-terre tax was a cornerstone of Mayor Mamdani’s campaign, designed to capture revenue from non-resident owners of luxury properties valued at over $5 million.
- April 2026: Mayor Mamdani officially unveils the framework for the pied-a-terre tax, framing it as a necessary measure to ensure that high-net-worth individuals contribute their "fair share" to city infrastructure and social services.
- July 2026: The Department of Finance releases the supplemental roll of 900,000 properties identified as potentially liable for the tax. Critics quickly label this the "rich hit list," citing concerns over data privacy and administrative overreach.
- August 2026: Seven property owners file suit in Staten Island, challenging the DOF’s failure to cross-reference data before issuing notices.
- August 12, 2026: The city receives updated 2025 income-tax data from the state, leading the DOF to clear 1,210 property owners who had previously been flagged.
- September 29, 2026: Justice Wayne Ozzi rules in favor of the homeowners, granting injunctive relief and halting the rollout of the notices.
- October 2026: The Appellate Division, Second Department, hears oral arguments and reverses the lower court’s decision just one week later.
Legal Reasoning and the Question of Standing
The court’s decision rests on a strict interpretation of what constitutes a "cognizable injury" in the context of administrative law. The appellate judges noted that the plaintiffs’ grievances—ranging from the inconvenience of applying for an exemption to the fear of being identified as a luxury property owner—did not rise to the level of a constitutional or statutory violation.
The court pointedly noted that the city’s annual assessment rolls are already public documents, which contain detailed information about property valuations and ownership. Given this existing transparency, the court found the plaintiffs’ arguments regarding privacy and the potential for "stalking or fraud" to be "generalized, tenuous, and ephemeral." Furthermore, the court dismissed the argument that the time and financial costs associated with filing for an exemption constituted an injury. The judges remarked that all tax compliance regimes require some expenditure of effort from citizens, and the petitioners failed to provide evidence that their specific costs were excessive or unique.
Significantly, the panel rejected the city’s attempt to have the case dismissed on the grounds of mootness—noting that the issues raised by the plaintiffs regarding the methodology of the rollout were of sufficient public importance to warrant a decision on standing, even if some of the petitioners had already been granted exemptions.
Economic Implications and Revenue Projections
The financial stakes of the pied-a-terre tax are substantial. Comptroller Mark Levine initially projected that the tax could generate up to $380 million annually from approximately 11,200 properties. Mayor Mamdani’s administration has maintained a more optimistic outlook, estimating the annual yield at $500 million.
The city’s shift in strategy following the receipt of updated tax data demonstrates the complexity of the implementation. The DOF has already granted over 8,800 exemption requests, suggesting that the initial net of 17,000 notices was indeed over-inclusive. Despite this, the administration remains firm that the process is functioning as intended. The existence of the exemption mechanism, according to the court, serves as the primary safeguard against the exact type of "imperfect" notice distribution that the plaintiffs decried.
Official Responses and the Road Ahead
Mayor Mamdani characterized the court’s ruling as a decisive victory for economic equity. In an official statement following the announcement, he framed the lawsuit as an attempt by the "ultrawealthy" to circumvent their tax obligations.
"Owning a second home worth over $5 million should come with a responsibility to the city that makes it valuable," the Mayor said. He further signaled that the administration is prepared for a long legal battle, noting that there are "ongoing challenges in Suffolk County" brought by similar interest groups. Mamdani concluded by reiterating his commitment to a fair and efficient implementation of the surcharge, emphasizing that the revenue is vital for building a city that "works for everyone."
Legal experts observing the case suggest that while this ruling provides the city with a significant tactical advantage, it does not represent the end of the legal war. The separate challenges pending in other jurisdictions will likely test different aspects of the law, potentially including the scope of the city’s authority to impose such a tax without broader state legislative endorsement or specific regulatory alignment.
Broader Implications for NYC Tax Policy
The dismissal of this lawsuit reinforces a trend in New York administrative law: courts are generally hesitant to intervene in the early stages of tax collection efforts unless there is a clear showing of irreparable, non-monetary harm. By placing the burden on the taxpayer to prove residency through the established exemption process, the city has maintained its ability to act as the primary arbiter of tax liability.
For the real estate sector and high-net-worth investors, the ruling serves as a stark reminder that the city’s tax assessment machinery is increasingly integrated. The use of supplemental rolls and the rapid, data-driven adjustment of these lists signal a more aggressive approach by the Department of Finance. As the city continues to navigate fiscal pressures, the precedent set by this case—that administrative errors in the rollout of a tax do not inherently grant a right to legal relief—will likely be cited in future disputes over municipal taxation.
As the city moves forward, the focus will now shift to the efficiency of the exemption process itself. If the DOF can continue to process the remaining thousands of requests with speed and accuracy, the political fallout from the "hit list" may subside. However, should the city encounter further administrative hurdles or public backlash regarding the handling of sensitive taxpayer data, the legal challenges currently percolating in the courts could gain renewed momentum. For now, however, the pied-a-terre tax stands on firm legal ground, and the city’s treasury department has been given the green light to proceed with one of the most ambitious revenue-generating schemes in recent New York history.