The Economic Resilience of the United States in the Face of Triple-Digit Oil Prices

When global energy markets witnessed Brent crude oil prices breach the psychologically significant $100-per-barrel threshold this week, the reaction from the financial community was remarkably muted compared to historical precedents. In previous decades, such a rapid ascent in energy costs—driven largely by geopolitical volatility and the specter of conflict in the Middle East—would have triggered immediate panic, stock market sell-offs, and fears of a looming recession. However, the current economic landscape suggests that the United States is far better equipped to weather a crude oil price spike than it was during the energy crises of the 1970s and 1980s. While economists are keeping a close watch on inflationary pressures and consumer sentiment, the consensus is that $100 oil no longer represents the same existential threat to the American economy that it once did.
Brent crude climbed to approximately $110 a barrel on Monday, marking a 4% increase and reaching its highest valuation since May. By Tuesday, the price had moderated slightly to around $107. This upward momentum, fueled by concerns over supply chain disruptions and the escalation of conflict involving Iran, has inevitably drawn comparisons to the oil shocks of the past. Yet, experts argue that the structural composition of the U.S. economy has fundamentally shifted, rendering the nation more resilient to energy market volatility.
A Historical Context of Energy Consumption
To understand why the current price levels are less alarming, one must examine the evolution of the American consumer’s relationship with energy. According to analysis from JPMorgan, in 1980, Americans spent approximately 6% of their total disposable income on gasoline. This high percentage was the result of a combination of lower fuel efficiency in vehicles, higher per-capita fuel consumption, and lower inflation-adjusted income levels.
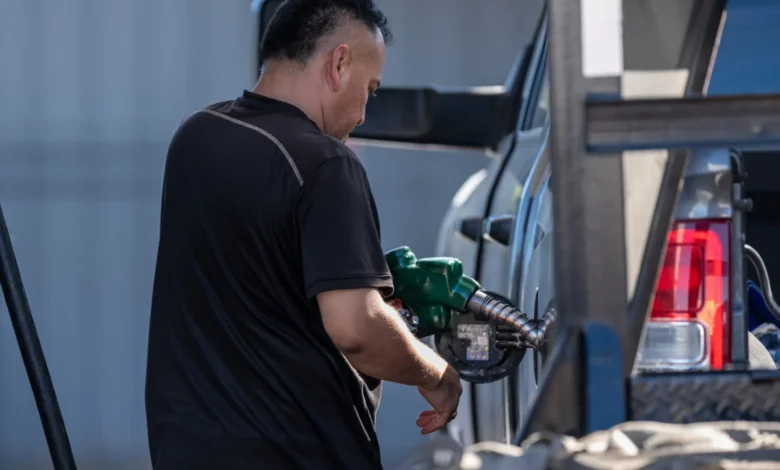
In contrast, contemporary data indicates that the share of income spent on gasoline by the average American household now hovers around 2.5%. This decline is attributable to several factors: the rise of fuel-efficient vehicles, the gradual electrification of the transportation sector, and a significant increase in real median household income over the last four decades. Because gasoline represents a smaller slice of the household budget, price fluctuations are less likely to result in the drastic, systemic curtailment of non-essential spending that defined previous eras of high oil prices.
The Paradigm Shift: From Importer to Exporter
Perhaps the most significant development in the domestic energy landscape is the transformation of the United States into a net energy exporter. Historically, the U.S. was highly vulnerable to global supply shocks, as its reliance on foreign crude made the domestic economy a "price taker" at the mercy of global supply chains. Today, the domestic production boom—driven by advancements in shale extraction and deep-water drilling—has created a buffer.
Michael Pearce, chief U.S. economist at Oxford Economics, notes that while higher oil prices remain a net negative for household budgets, they act as a stimulus for the robust domestic energy production sector. "There is not a ‘tipping point’ for crude oil prices that will trigger an automatic economic recession," Pearce observed. This duality—where the pain at the gas pump is partially offset by gains in the domestic energy sector’s profitability and employment—creates a dynamic that is entirely different from the crises of the 20th century.
The Real Concern: Refined Product Shortages
While crude oil prices garner the headlines, economists are increasingly focusing on the divergence between crude prices and the prices of refined fuels, such as gasoline and diesel. The concern is not merely the cost of raw oil, but the bottleneck in refinery capacity. Even if oil prices were to stabilize, a shortage in the ability to process that oil into usable fuel keeps prices at the pump artificially elevated.
This is a critical distinction for the broader economy. Gasoline costs directly impact the discretionary income of the average household, potentially slowing consumer spending. However, diesel is the lifeblood of the American industrial engine. It powers the heavy-duty trucks that transport goods, the tractors that drive the agricultural sector, and the machinery that sustains manufacturing plants. If diesel prices remain at their current record highs—with recent figures hitting $6.39 per gallon compared to $3.70 a year earlier—the inflationary impact is felt across the entire supply chain. Every item moved by truck becomes more expensive to deliver, and every farm-to-table product incurs higher production costs.
Chronology of the Current Price Surge
The recent climb in energy prices can be traced to a series of geopolitical escalations that have tightened the global supply-demand balance:
- Early September 2026: Tensions in the Middle East begin to escalate, leading to concerns regarding the safety of transit through critical shipping lanes.
- September 10, 2026: Market analysts report that the combination of regional instability and restricted refinery output has pushed diesel to record levels, causing anxiety among logistics providers.
- September 14, 2026: Brent crude breaks the $100 threshold, hitting $110 during intraday trading. Financial analysts begin assessing the potential for interest rate impacts as inflation concerns mount.
- September 15, 2026: Prices retreat slightly to $107 as traders digest the latest economic data and central bank commentary.
Implications for Inflation and Consumer Spending
The inflationary pressure of these energy costs remains a primary concern for the Federal Reserve and economic policymakers. Patrick De Haan, head of Petroleum Analysis at the gas tracking app GasBuddy, suggests that the benchmark of $100 is largely psychological. "In inflation-adjusted terms, oil would likely need to approach $200 per barrel to exert the same level of economic drag that $100 did in the past," De Haan explained.
Despite this, the cumulative effect of high prices is not negligible. Oxford Economics estimates that if current prices persist through the end of the year, they could reduce consumer spending growth by several tenths of a percentage point in 2027. This may not trigger a recession, but it represents a "tax" on the economy that diverts capital away from other growth-oriented sectors.
Disparate Impacts on Demographic Groups
The economic burden of high energy prices is not distributed equally. Lower-income Americans are disproportionately affected because a larger portion of their total expenditure is allocated to non-discretionary items, including food, housing, and energy. Unlike wealthier households, which may have the flexibility to adjust their spending or absorb higher costs, lower-income families have less "cushion" to withstand prolonged periods of elevated fuel costs.
Furthermore, these households are often more reliant on daily commuting and lack access to more efficient, newer-model vehicles, making them more exposed to volatile gas prices. While the economy as a whole may be able to "grimace and bear it," as De Haan describes the current situation, the pressure on vulnerable demographics could manifest as a decline in retail sales and an increase in debt-servicing issues as the holiday season approaches.
Outlook and Conclusion
The current energy environment is characterized by a complex interplay of geopolitical risk, structural market changes, and the lingering effects of supply chain constraints. While the U.S. economy has demonstrated remarkable resilience, the sustained elevation of fuel prices—particularly diesel—poses a persistent challenge to both consumer sentiment and industrial efficiency.
Most analysts agree that unless prices approach the $140-per-barrel range, the structural integrity of the U.S. economy is likely to remain intact. However, the ongoing refinement capacity issues and the potential for further geopolitical volatility mean that the energy sector will remain a primary focus for observers. For the time being, the market is betting on the ability of the U.S. to absorb these costs without falling into a significant downturn, marking a notable departure from the historical narrative of oil-induced economic crises. As the nation moves toward the final quarter of the year, the stability of energy prices will be a critical bellwether for the broader trajectory of the American economy.